Wall Street closed out a volatile week on a positive note, with major stock indexes posting solid gains as easing oil prices helped halt the sharp surge in Treasury yields that had rattled markets over the preceding several days. The Dow Jones Industrial Average climbed close to one percent, snapping a three-week losing streak, while both the S&P 500 and the technology-heavy Nasdaq Composite also notched weekly gains despite a genuinely turbulent stretch of trading throughout the week.
The turnaround in market sentiment coincided directly with news that the United States and Iran had moved closer to a potential agreement covering naval blockades on tankers moving through the Persian Gulf, alongside a possible easing of broader economic measures against Tehran. This apparent diplomatic progress helped push oil prices notably lower, providing meaningful relief to markets that had spent much of the week grappling with inflation concerns tied directly to elevated energy costs.
Benchmark borrowing costs, which had climbed to their highest levels in multiple decades earlier in the week amid persistent inflation worries and hawkish signals from Federal Reserve officials, finally halted their aggressive upward march as oil prices retreated. This pause in the bond market selloff provided welcome breathing room for equity investors, who had been closely watching rising yields as a potential threat to stock valuations, particularly for more richly priced growth and technology stocks that tend to be especially sensitive to changes in borrowing costs.
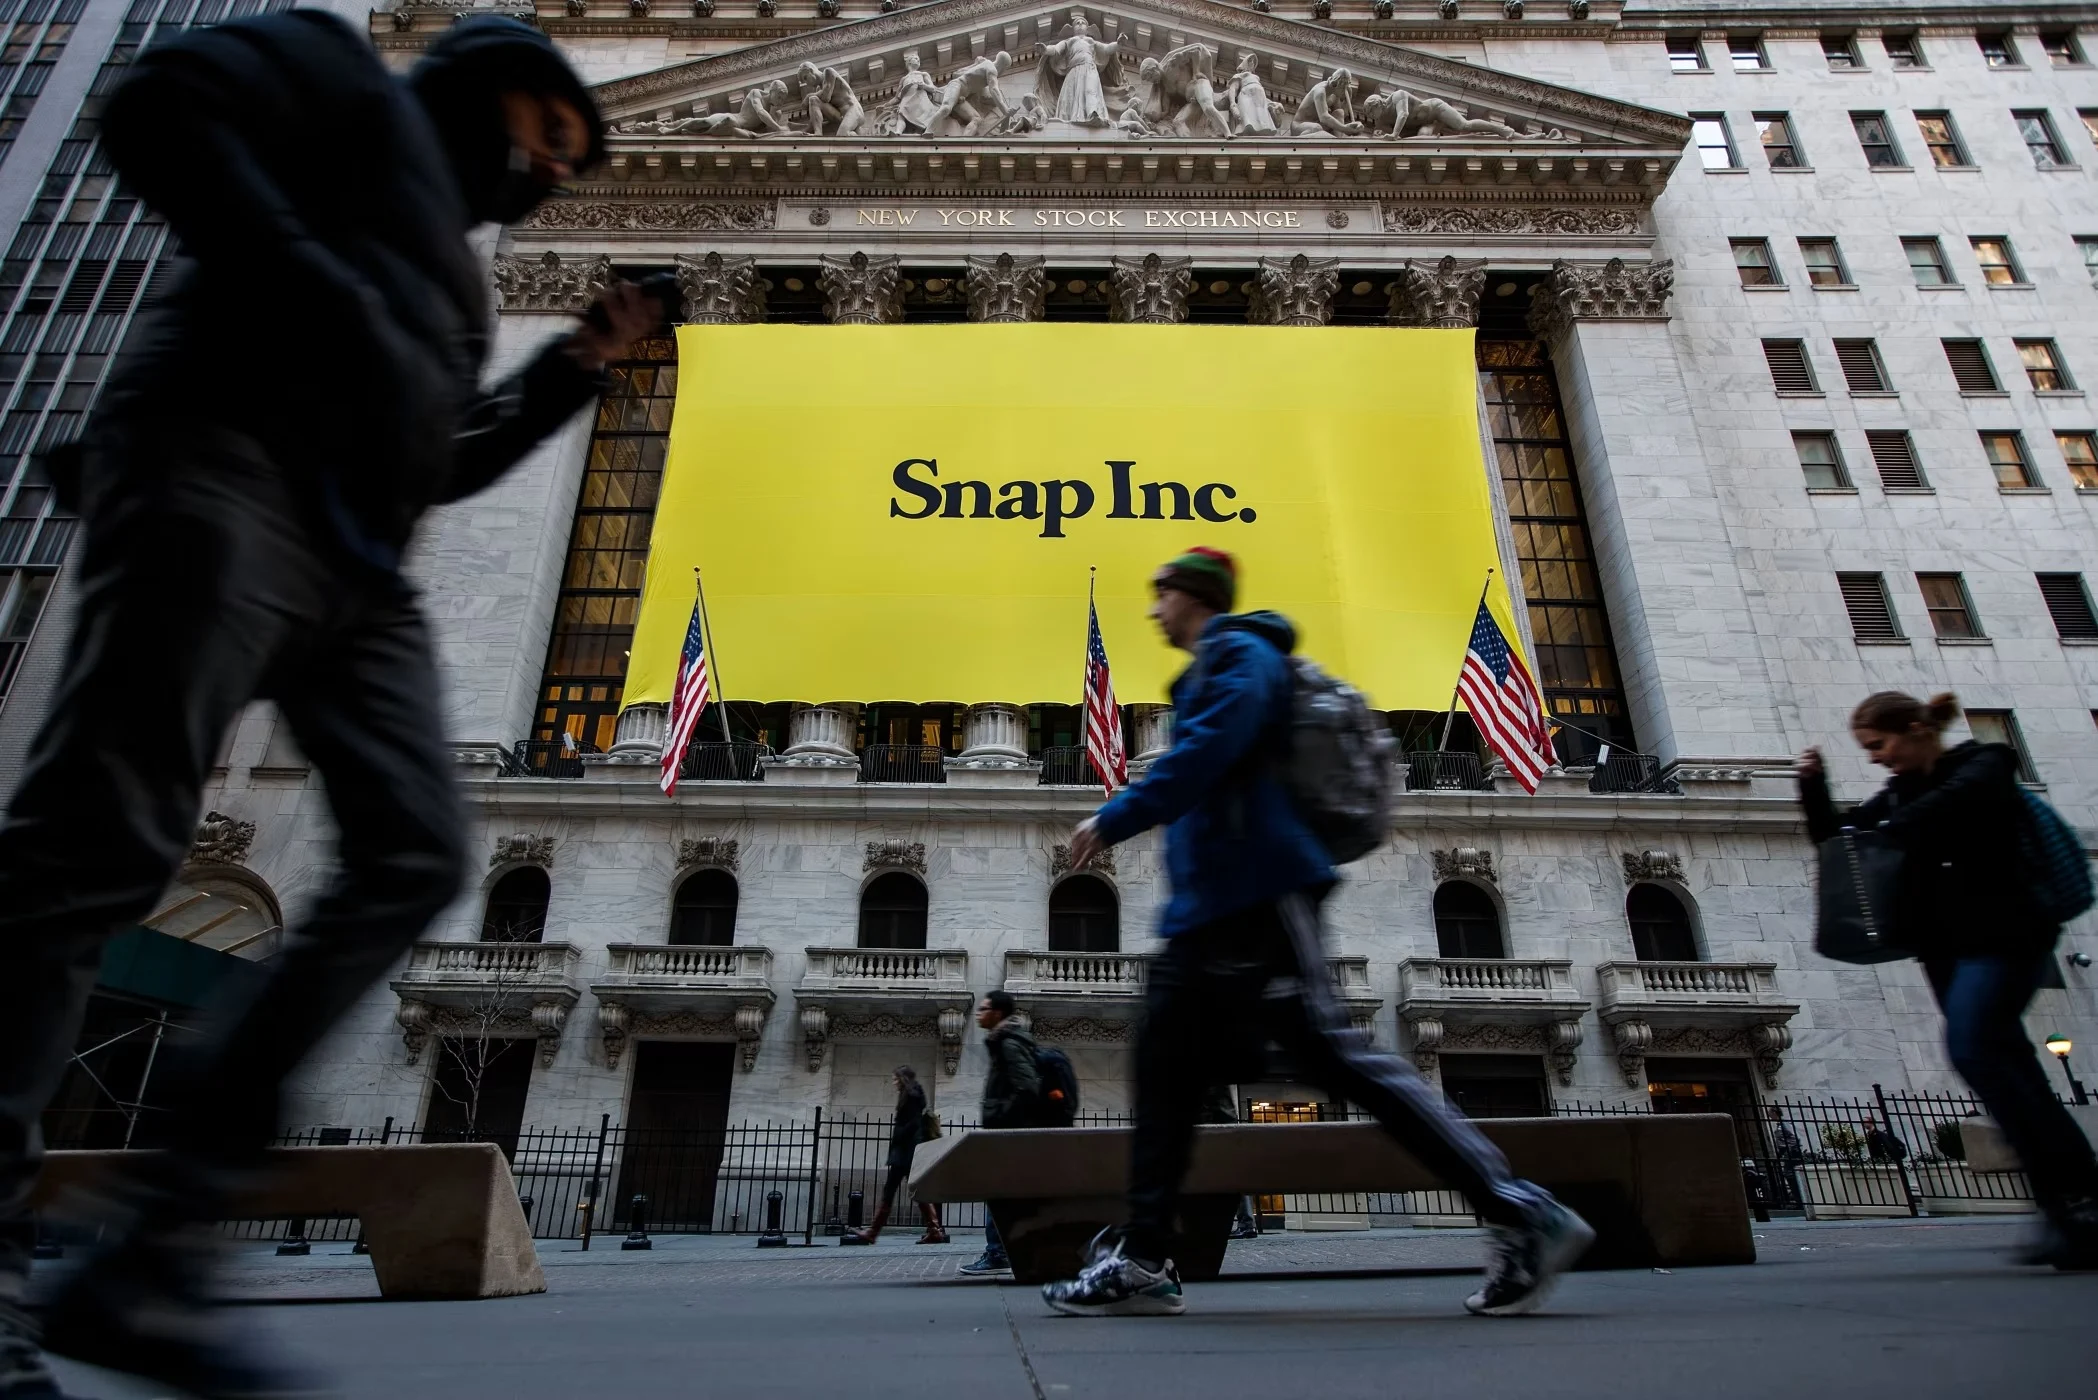
Technology stocks played a particularly important role in the week’s overall market performance, with continued optimism around artificial intelligence infrastructure spending helping offset some of the earlier pressure from rising yields. Individual companies showed considerable variation in performance throughout the week, with some technology names, including a major social media company, facing pressure amid investor concerns about competitive positioning in the fast-moving artificial intelligence race, even as broader sector sentiment remained generally constructive.
Corporate earnings expectations continued providing a fundamental floor of support for the broader market throughout this volatile stretch, even as geopolitical and policy uncertainty created what one market strategist described as a ceiling limiting how far stocks could climb. This characterization of corporate profitability providing support while external uncertainty caps upside potential has become an increasingly common framework for understanding market dynamics throughout much of this year’s trading environment.
Beyond the immediate market-moving headlines, the week’s broader economic backdrop included several other notable developments, including data showing unchanged demand for long-lasting goods such as defense and transportation equipment during August, a signal that suggested a degree of underlying economic stability even amid the more dramatic swings occurring in bond and energy markets throughout the same period.
As markets head into the coming week, attention remains focused on whether the apparent progress toward de-escalation between the United States and Iran can translate into more durable stability for both energy prices and the broader financial markets that have proven so sensitive to developments in this ongoing crisis. Investors will also be watching closely for any additional details emerging from this week’s high-profile summit between American and Chinese leaders, along with continued signals from Federal Reserve officials regarding the future path of interest rate policy.
