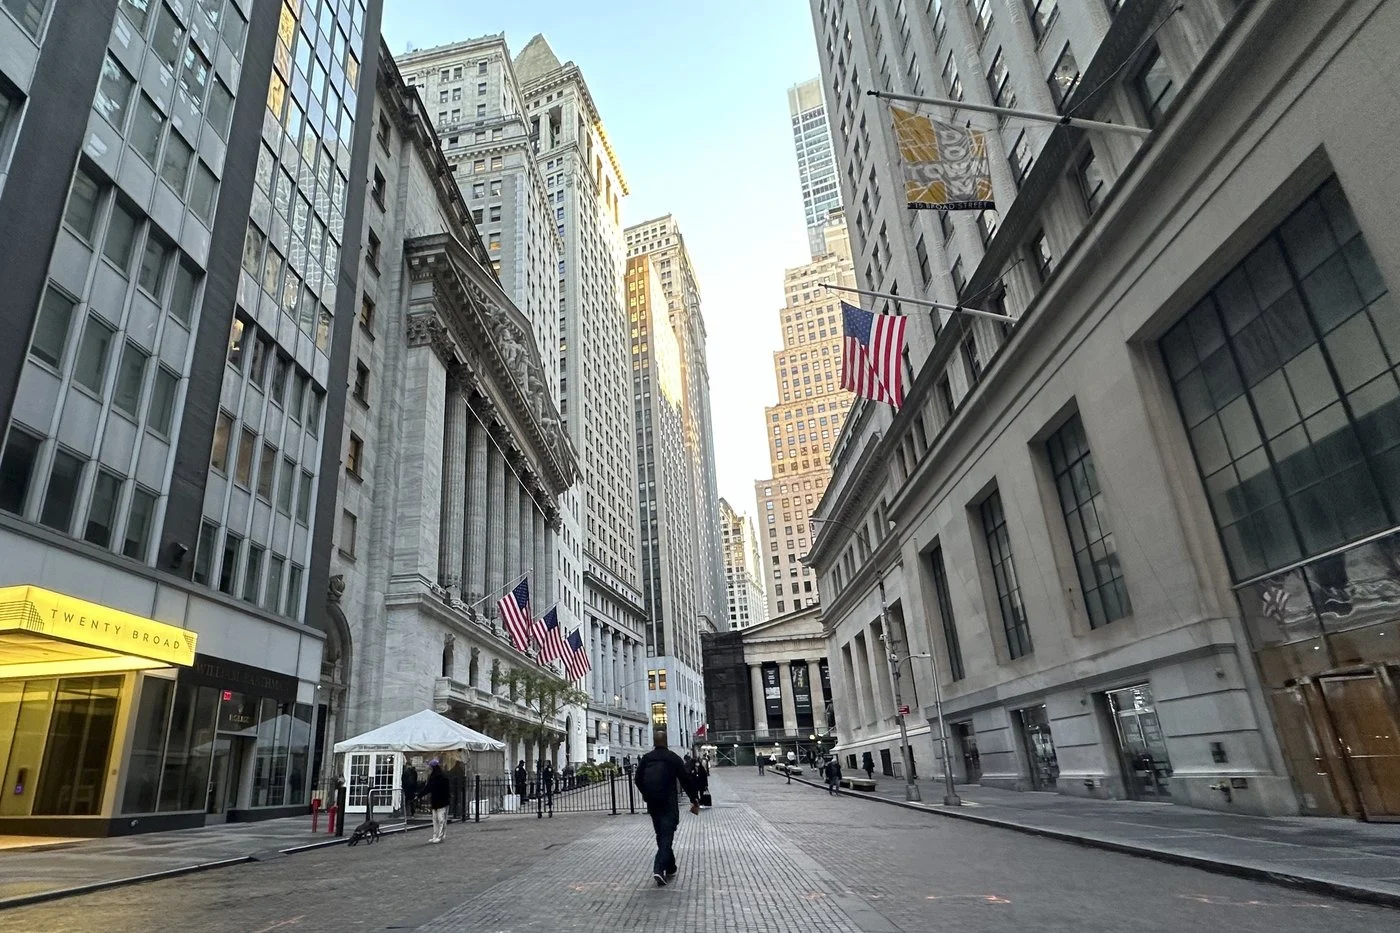
Wall Street spent Tuesday hovering just below its all-time highs, in a relatively quiet trading session that nonetheless carried significant undercurrents tied to global energy markets and corporate earnings expectations. The S&P 500 finished essentially unchanged, sitting only about 0.4 percent below the record it set last month, while the Dow Jones Industrial Average slipped modestly and the Nasdaq composite notched a small gain to reach its own new high. Traders described the mood as cautiously optimistic, with investors weighing strong underlying corporate performance against ongoing geopolitical uncertainty tied to the Middle East conflict.
Oil prices played a central role in shaping the day’s trading. Brent crude briefly dipped below ninety-eight dollars a barrel during the morning session, offering a moment of relief after weeks of elevated prices driven by instability in the region. Prices later climbed back somewhat, settling around one hundred dollars a barrel by the afternoon, but the intraday dip was enough to lift stocks temporarily and ease some of the inflation concerns that have weighed on markets throughout the summer. Analysts noted that even small movements in oil prices continue to carry outsized influence over broader market sentiment given how directly energy costs feed into inflation expectations and corporate input costs.
Corporate earnings expectations added another layer of optimism to the day’s trading. Many publicly traded companies are approaching the close of their third fiscal quarter, and early forecasts suggest another exceptionally strong period of growth. Analysts tracking companies in the S&P 500 currently project overall earnings growth of nearly twenty-nine percent compared to the same period last year, which would mark a third consecutive quarter of growth exceeding twenty-five percent if the estimates hold. Such sustained strength in corporate profits has historically supported higher stock valuations over time, giving investors reason for confidence even as other economic signals remain mixed.
Individual stock movements told their own stories throughout the session. Shares of a major Swiss sportswear company jumped more than ten percent after it unveiled ambitious long-term financial targets and approved a substantial stock buyback program worth up to one billion dollars through the end of the decade. Buybacks of this scale often signal management confidence in a company’s future cash flow and are typically well received by investors looking for signs of financial strength beyond quarterly earnings reports alone.
The broader technology sector continued to show resilience despite some lingering questions about whether artificial intelligence stocks have climbed too far, too fast. Chipmakers in particular have remained a bright spot for the market throughout the year, buoyed by continued strong demand for the specialized hardware needed to train and run advanced AI systems. This steady demand has helped offset weaker performance in other corners of the market and has become one of the defining stories of the current bull run.
Bond markets showed relatively little movement during the session, with Treasury yields holding in a familiar range after weeks of significant volatility tied to Federal Reserve policy decisions and broader inflation concerns. Currency markets similarly remained stable, reflecting a broader sense of calm that settled over financial markets even as geopolitical headlines continued to dominate news coverage throughout the day.
Looking ahead, investors are keeping a close watch on a major diplomatic summit scheduled for later this week between American and Chinese leaders, along with continued developments in the Middle East that could quickly shift oil prices and broader market sentiment in either direction. For now, markets appear content to hold steady near record territory, buoyed by strong corporate fundamentals even as external risks continue to simmer just beneath the surface of an otherwise calm trading environment.
